Insurance direct mail examples,
explained.
The 20 most common insurance mailers in 479,853 real pieces from 10,716 sender labels, with what they offer and how they ask people to respond.
What does insurance direct mail look like?
Most insurance mail arrives as an envelope with a letter and inserts (74.5%). The most common offer is a price or dollar amount (89.4%). Most pieces ask the reader to respond by calling (94.9%) or visiting a website (84.2%). The most common reason given to trust the offer is security or privacy language (58.9%).
The expanded catalog includes 479,853 eligible insurance pieces, with 479,831 analyzed across 10,716 observed sender labels. The median piece is 6 pages. Use this guide to plan one clear control and one-variable tests.
Source: Expanded Insurance sector extract from 2,213,774 eligible records. 2,213,652 records were analyzed; 122 were explicitly unknown. Analysis received August 15, 2026. The expanded catalog has 2,213,774 eligible physical-mail records; 2,213,652 were analyzed and 122 remain unknown. Industry tables cover 1,873,585 records with an assigned industry. Computer-assigned labels can contain errors.
The 20 most common insurance mailers
See how common Insurance mail packages the offer, proof, response path, and disclosures. Open any card to see every page. These are observed patterns, not performance rankings.
-
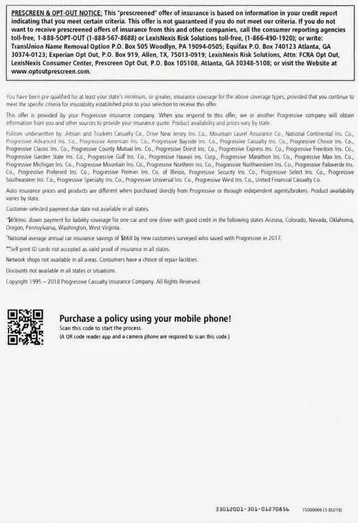
Progressive modular auto-savings package
Blue offer envelope, brand bridge panel, price-led letter, and dense terms page.
-
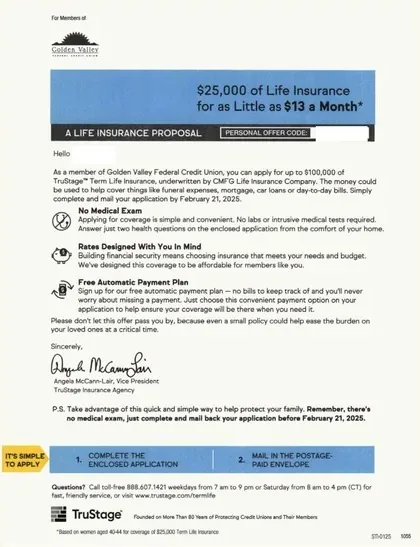
TruStage partner-branded life member-benefit system
Partner-branded envelope, member-benefit letter, blue or yellow benefit panel, and reply path.
-
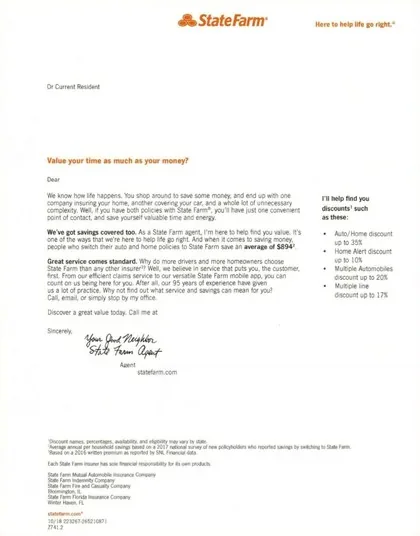
State Farm local-agent quote letter
Plain outer envelope and a short local-agent letter with one quote or contact action.
-
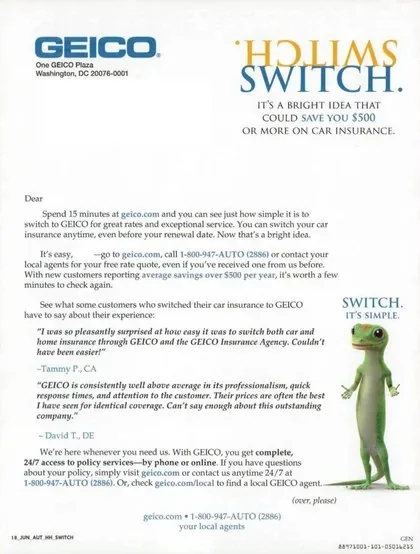
GEICO switch-and-save letter
Switch-and-save headline, short agent-style letter, and recurring gecko or GEICO brand device.
-
New York Life and AARP term-life package
AARP endorsement, term-life quote or eligibility detail, benefit table, and reply device.
-
AAA life rate-chart package
AAA affinity envelope, prominent rate table, eligibility copy, and phone or reply response.
-
Allstate auto quote comparison
Agent letter with a structured auto quote or coverage comparison table.
-
Cigna Medicare grocery-allowance notice
Notice format centered on a county-specific grocery allowance and a phone response.
See all 20 common mailers
-
Allstate home quote estimate
Home insurance estimate, premium table, agent letter, and coverage summary.
-
Credit-union group-auto switch package
Credit-union endorsement, member benefit amount, quote form, and insurer fulfillment.
-
Mutual of Omaha final-expense calculator package
Dark activation envelope, benefit calculator, rate grid, and phone or reply action.
-
United of Omaha confidential response package
Red confidential device, response deadline, qualification letter, and reply action.
-
Hartford and AARP experienced-driver offer
AARP endorsement, experienced-driver savings claim, quote code, and phone response.
-
AAA valued-member coverage package
Valued-member framing, affinity endorsement, coverage table, and eligibility response.
-
TruStage accidental-death enrollment package
Immediate-reply request, benefit summary, signature form, and dense coverage notice.
-
Assurance Medicare response letter
Plain envelope, urgent Medicare review copy, phone response, and separate disclosure page.
-
Amica premium auto quote
Premium-account-card device, comparison copy, quote number, and phone response.
-
Mutual of Omaha whole-life new-policy offer
New-policy-offer envelope, simple eligibility framing, and short application path.
-
Liberty Mutual group-auto benefit proposal
Member benefit framing, premium proposal, short application form, and reply path.
-
GoHealth Medicare notice
Official-notice visual language, local benefit amount, registration code, and phone response.
Each design groups similar mail pieces. The count covers the reviewed set, so the true total can be higher. A common design is not a proven winner.
Build a insurance mailer like these. Send it this week.
Upload your list, design the piece, and see the exact cost before you send. Sendvo prints, mails, and tracks delivery.
What insurance mail uses most
Share of pieces that include each element. One piece can include several, so rows add up to more than 100%.
Format
| Format | Bar | Share |
|---|---|---|
| Envelope + letter + inserts | 74.5% | |
| Envelope + letter/insert | 15.1% | |
| Folded self-mailer / short brochure | 7.8% | |
| Multi-page letter / brochure | 1.0% |
Offer
| Offer | Bar | Share |
|---|---|---|
| Price or payment | 89.4% | |
| Free | 74.4% | |
| Discount or savings | 60.1% | |
| Appointment or event | 28.1% |
Reason to trust the offer
| Reason to trust the offer | Bar | Share |
|---|---|---|
| Security or privacy | 58.9% | |
| Credentials or certification | 57.6% | |
| Guarantee or reduced risk | 46.8% | |
| Tenure or experience | 37.8% |
Way to respond
| Way to respond | Bar | Share |
|---|---|---|
| Phone | 94.9% | |
| Web address | 84.2% | |
| Apply or enroll | 67.8% | |
| Shop or order | 54.5% |
Scope: this insurance catalog. Not included: responses, sales, cost, or return on investment.
What does insurance mail need to do?
A good piece helps its intended audience take one reasonable next step.
For a household reviewing insurance coverage, this piece helps them request a quote or call and understand the important limits.
The job of the mail
Help a household decide whether to request a quote or call an agent.
The main problem
Price uncertainty, coverage complexity, trust, and switching effort.
The safest first move
Use this first message plan: Coverage type, qualified value, action, timing, eligibility. Envelope + Letter + Inserts is the leading observed format at 74.5% in this insurance catalog. Choose it only when it fits the reading job.
Counts describe observed mail, not results. These figures are not response rates, conversion rates, lift, cost, or return on investment.
How big is the insurance market in the data?
Start with the narrowest reliable market before you use a broad sector average.
Do not average health, life, and auto. Open the child page when that is the campaign.
This page uses the complete Insurance industry table: 479,853 eligible pieces, 479,831 analyzed records, and 10,716 observed sender labels.
Pieces found by market
See the market table and how to use it
| Market | Pieces | Share | Sender labels | What it means |
|---|---|---|---|---|
| Health Insurance | 155,288 | 32.4% | 3,043 | Largest insurance market. Separate guide. |
| Life Insurance | 132,599 | 27.6% | 509 | Median 10 pages. |
| Auto Insurance | 97,437 | 20.3% | 574 | Coverage mail. Not vehicle-service mail. |
| Medicare Advantage | 79,827 | 16.6% | 1,095 | Separate legal and review needs. |
| Property Insurance | 23,785 | 5.0% | 674 | Separate from auto insurance. |
Use the narrowest reliable market row for the campaign. Parent-sector patterns stay labeled as parent context.
Who is the reader, and why now?
A useful message begins with a real reason for the mail to arrive now.
A real reason to arrive
household comparing coverage
A clear concern
a savings claim with no basis
A small next step
Call or request a quote. Phone is a path on 94.9% of insurance pieces; apply-or-enroll is 67.8%.
“For a household reviewing insurance coverage, this piece helps them request a quote or call and understand the important limits.”
Use this sentence in the campaign brief. If it names several unrelated audiences, split the campaign.
See the computer-assigned audience and buying-stage labels
These labels come from words found in the mail. They do not come from verified mailing lists.
| Audience label | Pieces | Share |
|---|---|---|
| Homeowner Or Household | 267,257 | 55.7% |
| Existing Customer | 246,795 | 51.4% |
| New Prospect | 199,460 | 41.6% |
| Older Adult Or Retiree | 169,177 | 35.3% |
| Borrower Or Credit Seeker | 90,704 | 18.9% |
| Small Business | 86,800 | 18.1% |
| Traveler Or Guest | 40,690 | 8.5% |
| Donor Or Supporter | 17,411 | 3.6% |
| Lapsed Or Winback | 7,361 | 1.5% |
| Buying-stage label | Pieces | Share |
|---|---|---|
| Awareness Or Education | 405,878 | 84.6% |
| Consideration Or Comparison | 371,630 | 77.4% |
| Decision Or Action | 368,616 | 76.8% |
| Retention Or Cross Sell | 85,403 | 17.8% |
| Renewal or win-back | 62,794 | 13.1% |
How does insurance mail start the conversation?
Use these patterns to understand the market. Do not copy them without a reason.
A message pattern is the order of the offer, proof, and next step. These patterns come from this insurance catalog. They show what appeared often. They do not show what worked.
Lead with a real incentive
Use when a bonus or gift is the reason to act.
Watch for: The bonus can hide fees or eligibility.Renew or win back a customer
Use when the reader already has a relationship.
Watch for: Sounds like cold acquisition if the account context is missing.Ask for a quote or a conversation
Use when the next step is a quote, not an application.
Watch for: A quote request that reads like enrollment.Explain first, then ask for one action
Use when this sequence fits better than the leading cluster.
Watch for: Interchangeable if you copy the category wholesale.See all message-pattern data
| Message pattern | Pieces | Share |
|---|---|---|
| Lead with an incentive | 350,448 | 73.0% |
| Renewal or win-back | 61,359 | 12.8% |
| Mission Or Donation Appeal | 18,826 | 3.9% |
| Quote or consultation | 12,140 | 2.5% |
| Explain, then ask for one action | 12,115 | 2.5% |
| Rate Led Financial Acquisition | 11,014 | 2.3% |
| Trust Led Education | 9,190 | 1.9% |
| Customer Cross Sell Or Service | 4,021 | 0.8% |
| Deadline Driven Offer | 718 | 0.1% |
Use the leading pattern as a control only when it matches the reader and the next step.
What formats do insurance mailers use?
The leading format comes from this insurance catalog. It is not a performance result.
Envelope + Letter + Inserts
This is the leading format in this insurance catalog. Use it as a control only when the reader needs that amount of explanation.
Insurance pieces have a median length of 6.0 pages and 1141.6 characters per page. Median response-step complexity is 10.00; median disclosure balance is 0.421.
Compare all observed format labels
These are computer-assigned format labels. They are not production specifications.
| Format label | Pieces | Share |
|---|---|---|
| Envelope + Letter + Inserts | 357,271 | 74.5% |
| Envelope + Letter/Insert | 72,272 | 15.1% |
| Folded Self-Mailer / Short Brochure | 37,265 | 7.8% |
| Multi-Page Letter / Brochure | 4,718 | 1.0% |
| Booklet / Catalog | 3,973 | 0.8% |
| Short Multi-Component Package | 3,259 | 0.7% |
| Single-Piece Mailer; Geometry Unavailable | 1,072 | 0.2% |
| Uncertain Physical Format | 1 | 0.0% |
What goes in each part of the package?
Each part of the package should answer one question for the reader.
Envelope
Show relevance. Do not place the full sales claim outside.
Opening
Name the reader and the reason for contact.
Offer
State coverage, premium, deductible in one clear reading path.
Proof
Use licensed-agent access, carrier strength, tenure, ratings, local presence, and qualified savings only with a basis.
Next step
Call or request a quote. Phone is a path on 94.9% of insurance pieces; apply-or-enroll is 67.8%.
Disclosures
Place an important limit near the claim that it changes.
See the observed page and component labels
| Page job | Pieces | Share |
|---|---|---|
| Exterior Or Lead Page | 479,830 | 100.0% |
| Ask for a response | 476,891 | 99.4% |
| Address a concern | 472,273 | 98.4% |
| State the offer | 464,460 | 96.8% |
| Give proof or reassurance | 437,584 | 91.2% |
| State limits or disclosures | 408,997 | 85.2% |
| Explain Or Support | 340,265 | 70.9% |
| Component | Pieces | Share |
|---|---|---|
| Letter | 429,543 | 89.5% |
| Outer Envelope | 429,543 | 89.5% |
| Insert Or Terms Pages | 365,962 | 76.3% |
| Reply Device | 156,494 | 32.6% |
| Voucher Coupon Or Certificate | 88,037 | 18.3% |
| Self Mailer Body | 37,265 | 7.8% |
| Card Carrier Device | 7,420 | 1.5% |
| Undetermined Component | 3,992 | 0.8% |
| Booklet Or Catalog Body | 3,973 | 0.8% |
How should the copy read?
The reader should not need insurance expertise to understand the offer.
Write from the reader’s decision. Do not write from the company structure. Use common words. Define a specialist term the first time you use it.
Great coverage for everyone. Save big. Act now!
If you want to review [auto / home / health] coverage, request a quote or call. Any savings example is limited to the assumptions printed next to it. A quote is not a policy.
Useful sentence patterns
- When [situation], [audience] can review [coverage type] with [one proof] and request a quote.
- Request a quote for [coverage]: [qualified value], [action], [limit].
See the observed message-sequence labels
| Message sequence | Pieces | Share |
|---|---|---|
| Offer → Next Step → Proof → Qualification | 32,455 | 6.8% |
| Offer → Next Step → Qualification → Proof | 18,471 | 3.8% |
| Next Step → Offer → Proof → Qualification | 17,612 | 3.7% |
| Offer → Next Step → Qualification → Proof → Problem | 14,977 | 3.1% |
| Proof → Offer → Next Step → Qualification | 14,445 | 3.0% |
| Offer → Proof → Next Step → Qualification | 14,427 | 3.0% |
| Proof → Qualification → Offer → Next Step → Problem | 12,022 | 2.5% |
| Offer → Next Step → Proof → Qualification → Problem | 11,547 | 2.4% |
| Offer → Qualification → Next Step → Proof | 11,177 | 2.3% |
| Proof → Offer → Next Step → Qualification → Problem | 10,685 | 2.2% |
| Next Step → Offer → Qualification → Proof | 10,528 | 2.2% |
| Offer → Proof → Qualification → Next Step | 9,962 | 2.1% |
| Proof → Next Step → Qualification → Offer → Problem | 8,912 | 1.9% |
| Proof → Next Step → Offer → Qualification | 8,521 | 1.8% |
| Offer → Next Step → Proof | 7,939 | 1.7% |
| Next Step → Offer → Qualification | 7,216 | 1.5% |
| Next Step → Proof → Offer → Qualification | 7,084 | 1.5% |
| Offer → Next Step → Qualification | 6,931 | 1.4% |
| Next Step → Offer → Proof → Qualification → Problem | 6,690 | 1.4% |
| Next Step → Qualification → Offer → Proof → Problem | 6,594 | 1.4% |
| Offer → Proof → Next Step → Qualification → Problem | 6,563 | 1.4% |
| Proof → Qualification → Offer → Next Step | 5,966 | 1.2% |
| Proof → Offer → Qualification → Next Step → Problem | 5,923 | 1.2% |
| Proof → Next Step → Offer → Qualification → Problem | 5,855 | 1.2% |
| Offer → Next Step | 5,850 | 1.2% |
| Next Step → Offer → Proof | 5,806 | 1.2% |
| Next Step → Offer | 5,753 | 1.2% |
| Offer → Next Step → Proof → Problem → Qualification | 5,589 | 1.2% |
| Next Step → Offer → Qualification → Proof → Problem | 5,583 | 1.2% |
| Proof → Offer → Next Step | 5,566 | 1.2% |
| Proof → Offer → Qualification → Next Step | 5,548 | 1.2% |
| Next Step → Qualification → Offer → Proof | 5,546 | 1.2% |
| Qualification → Offer → Next Step → Proof | 5,502 | 1.1% |
| Offer → Proof → Qualification → Next Step → Problem | 5,384 | 1.1% |
| Offer → Qualification → Next Step → Proof → Problem | 5,339 | 1.1% |
| Qualification → Offer → Next Step → Proof → Problem | 5,136 | 1.1% |
| Proof → Qualification → Next Step → Offer | 4,896 | 1.0% |
| Offer → Proof → Next Step | 4,761 | 1.0% |
| Offer → Qualification → Proof → Next Step | 4,753 | 1.0% |
| Proof → Next Step → Offer | 4,735 | 1.0% |
| Next Step → Proof → Offer → Qualification → Problem | 4,573 | 1.0% |
| Qualification → Offer → Proof → Next Step | 4,343 | 0.9% |
| Next Step → Proof → Offer | 3,934 | 0.8% |
| Qualification → Next Step → Offer → Proof | 3,711 | 0.8% |
| Proof → Offer → Problem → Next Step → Qualification | 3,642 | 0.8% |
| Proof → Next Step → Qualification → Offer | 3,588 | 0.7% |
| Proof → Offer → Next Step → Problem → Qualification | 3,401 | 0.7% |
| Qualification → Next Step → Proof → Offer | 3,350 | 0.7% |
| Proof → Qualification → Next Step → Offer → Problem | 3,296 | 0.7% |
| Offer → Next Step → Problem → Proof → Qualification | 2,979 | 0.6% |
What offers appear most in insurance mail?
A clear offer states the value, the action, the timing, and who can use it.
Keep these four parts in one reading path. The offer becomes hard to understand when the reader must search for a limit or a deadline.
See offer and qualification data
| Offer label | Pieces | Share |
|---|---|---|
| Price Or Payment | 428,883 | 89.4% |
| Free | 357,239 | 74.4% |
| Discount Or Savings | 288,464 | 60.1% |
| Appointment Or Event | 134,627 | 28.1% |
| Reward Or Bonus | 62,688 | 13.1% |
| Rate Or APR | 31,436 | 6.6% |
| Bundle | 21,871 | 4.6% |
| Fee Waiver | 863 | 0.2% |
| Donation Match | 243 | 0.1% |
| Qualification level | Pieces | Share |
|---|---|---|
| High | 169,977 | 35.4% |
| Moderate | 152,028 | 31.7% |
| Low | 142,277 | 29.7% |
| None Or No Offer | 15,549 | 3.2% |
How does the mail make the offer believable?
Trust grows when a claim, its evidence, and its limit stay together.
What do you want the reader to believe?
What fact, credential, or process supports it?
What condition changes the meaning?
Assign an owner to every important claim before design begins. Keep the evidence file, the limit, and the approval date with the claim.
See proof and objection data
| Proof label | Pieces | Share |
|---|---|---|
| Security Or Privacy | 282,870 | 58.9% |
| Credentials Or Certification | 276,370 | 57.6% |
| Guarantee or reduced risk | 224,598 | 46.8% |
| Tenure Or Experience | 181,386 | 37.8% |
| Testimonial | 171,645 | 35.8% |
| Local Presence | 169,464 | 35.3% |
| Rating Or Award | 166,744 | 34.7% |
| Process Explanation | 48,821 | 10.2% |
| Product Or Service Detail | 43,184 | 9.0% |
| Customer Or Scale Count | 2,101 | 0.4% |
| Concern addressed | Pieces | Share |
|---|---|---|
| Price Or Affordability | 420,798 | 87.7% |
| Time Or Urgency | 417,855 | 87.1% |
| Eligibility Or Qualification | 321,081 | 66.9% |
| Risk Or Security | 300,821 | 62.7% |
| Trust Or Credibility | 291,629 | 60.8% |
| Effort Or Convenience | 261,357 | 54.5% |
| Switching Or Change | 124,644 | 26.0% |
| Commitment Or Contract | 26,484 | 5.5% |
How should the piece look?
Use layout to reduce uncertainty. Do not use decoration as proof.
Review the printed piece at its real size. Also hold it at arm’s length. Check it under normal household light.
See observed visual labels
A visual label means the system found an image idea near text. It is not a pixel measurement.
| Visual label | Pieces | Share |
|---|---|---|
| Image Led | 479,778 | 100.0% |
| People Or Lifestyle Text Adjacent | 342,971 | 71.5% |
| Product Or Service Text Adjacent | 278,453 | 58.0% |
| Diagram Or Comparison Text Adjacent | 203,114 | 42.3% |
| Copy Led | 40 | 0.0% |
| Balanced Image Copy | 12 | 0.0% |
When does personal data help?
Relevance comes from the reason for contact, not from a printed name alone.
Use personal data only when it is accurate, useful, and suitable for the message. Do not expose sensitive information on the envelope.
Connect each personal fact to a useful reason for contact. Create a safe fallback for every missing field. Print and check every variable version.
See observed personalization labels
| Personalization label | Pieces | Share |
|---|---|---|
| Local Or Geographic | 290,838 | 60.6% |
| Named Recipient Or Salutation | 277,238 | 57.8% |
| Product Specific Recommendation | 181,926 | 37.9% |
| Named Representative | 143,287 | 29.9% |
| Customer Or Account Context | 121,483 | 25.3% |
| Deadline Or Renewal Date | 115,999 | 24.2% |
| Unique Code Or Web Address | 25,964 | 5.4% |
| Selected Or Prequalified | 9,579 | 2.0% |
Named-recipient language is 57.8% of pieces and 14.8% on an equal-brand mean.
Large mailers can inflate the piece-weighted rate.
Name-on-the-letter is not a strategy.
How do readers respond?
Two response paths can work together when one is clearly primary.
94.9% in this insurance catalog. Observed frequency does not set its role in your brief.
84.2% in this insurance catalog. Choose one primary path for the campaign.
Phone or quote as primary; one URL. Same limits on the landing page.
See response-path and next-step data
| Response path | Pieces | Share |
|---|---|---|
| Phone | 455,495 | 94.9% |
| Web Address | 404,180 | 84.2% |
| Apply Or Enroll | 325,181 | 67.8% |
| Shop Or Order | 261,501 | 54.5% |
| Reply Mail | 156,494 | 32.6% |
| Appointment Or Quote | 152,080 | 31.7% |
| Qr | 26,499 | 5.5% |
| Donation | 6,202 | 1.3% |
| Store Or Location | 2,623 | 0.5% |
| Main next step | Pieces | Share |
|---|---|---|
| Phone | 192,060 | 40.0% |
| Apply Or Enroll | 129,593 | 27.0% |
| Web Address | 77,969 | 16.2% |
| Shop Or Order | 39,062 | 8.1% |
| Appointment Or Quote | 30,044 | 6.3% |
| Reply Mail | 4,975 | 1.0% |
| None Detected | 3,055 | 0.6% |
| Qr | 2,002 | 0.4% |
| Donation | 820 | 0.2% |
| Store Or Location | 251 | 0.1% |
Where do disclosures belong?
A limit should explain a true claim. It should not rescue a misleading one.
The main claim must be true on its own. Place a material limit where the reader will see it with the claim.
Review these topics
- rates
- eligibility
- coverage limits
- exclusions
- licensing
- Medicare language
This guide is not legal or financial advice. It does not promise approval, eligibility, savings, coverage, or investment performance. The licensed firm owns its rates, terms, eligibility, and approval decisions.
See disclosure-balance data
| Disclosure balance | Pieces | Share |
|---|---|---|
| Promotion and limits are balanced | 284,587 | 59.3% |
| Promotion is more prominent | 90,084 | 18.8% |
| Disclosure Heavy | 78,472 | 16.4% |
| Little promotion or qualification | 26,688 | 5.6% |
When should insurance mail arrive?
Plan from the in-home date. Use urgency only when the deadline is real.
Choose the date when the household should receive the mail.
Allow time to read, compare, and ask questions.
Use a real deadline only when the offer has one.
Keep the mailed promise in the quote page and call.
Plan from a real renewal or election date only if the list has it.
Time comparisons use only 1,242,943 records with a usable date (56.1459% of the eligible catalog). The remaining 970,831 records stay in full-catalog counts but do not enter time comparisons. Treat any time pattern as descriptive, not causal.
How do you stand out without overclaiming?
A strong difference helps the reader understand or trust the offer.
The largest senders can make a design choice look common. Compare the number of pieces with the number of sender labels that use the same choice.
Use one clear audience, useful proof, and one main response path.
A quote-and-reassurance market. Differentiate with one coverage job and one proof, not a louder discount.
Do not use a louder claim only to look different.
See sender concentration measures
The data has 10,716 sender labels.
The ten largest sender labels in this insurance catalog account for 43.8% of pieces.
The largest sender label in this insurance catalog is UnitedHealthcare (16,164 pieces).
What does a practical first insurance campaign look like?
Build a clear first version. Then change one item in each test.
- 01
Set the goal
Collect a quote request or a qualified agent call.
- 02
Write one audience sentence
For a household reviewing insurance coverage, this piece helps them request a quote or call and understand the important limits.
- 03
Choose the first version
Lead with a real incentive is the leading observed message pattern at 73.0% in this insurance catalog. Use it only when it fits the reader and decision. Coverage type, qualified value, action, timing, eligibility.
- 04
Choose the package
Envelope + Letter + Inserts is the leading observed format at 74.5% in this insurance catalog. Choose it only when it fits the reading job.
- 05
Set the response path
Phone or quote as primary; one URL. Same limits on the landing page.
- 06
Prepare proof and final checks
Carrier or agent evidence with an owner. Claim ledger, exclusion placement, licensing, URL/phone, seed piece.
Change one item at a time
- Control: one coverage + one qualified incentive + one proof.
- Cell A: opening only.
- Cell B: proof only.
Final review checklist
Use this list before the piece goes to print.
Do
- Pick one type of insurance before you write.
- Put the limit next to any savings language.
- Use a letter package when exclusions matter.
- Give every component one job.
- Use the Financial Services and Insurance page for Sendvo product help.
- Track phone calls and web responses separately.
- Assign a proof owner.
- Use the same coverage type on the mail and the web page.
- Check the disclosure size on a printed sample.
Do not
- Do not average health, life, and auto.
- Do not promise savings or approval.
- Do not treat frequency as effectiveness.
- Do not invent a trend.
- Do not put three coverage types in the first version.
- Do not hide exclusions.
- Do not paste competitor copy.
- Do not claim better results without result data.
- Do not treat a printed name as the full relevance plan.
Questions a new reader may ask
These answers explain the data and its limits.
Does a high piece count mean this mail works?
No. A large count only shows what reached the mailbox. It does not show response, sales, cost, or return on investment.
Does this guide promise a quote, price, coverage, or savings?
No. The carrier or licensed firm owns all quotes, prices, coverage, eligibility, and approval. This guide only explains patterns in the mail catalog.
Where can I plan an insurance campaign in Sendvo?
Use the Financial Services and Insurance solution page.
Why is Medicare Advantage separate?
The catalog has 79,827 Medicare Advantage pieces. This market also has different legal and review needs.
Are the format and audience labels exact?
No. A computer assigned these labels from words, page counts, and nearby visual evidence. Use the labels to plan a test. Do not treat them as a proven production plan.
How to read the data
The appendix keeps the evidence visible. It also marks the limits of the research.
2,213,774 physical-mail records meet the archive’s eligibility rules; 2,213,652 were analyzed and 122 remain unknown.
1,873,585 records have an assigned industry. 340,189 do not and are excluded from industry tables.
1,242,943 records have a usable date (56.1459%). 970,831 remain undated.
There are no response, conversion, revenue, cost, lift, or return fields. A common pattern is not a proven winner.
Open the full appendix
| Page job | Pieces | Share |
|---|---|---|
| Exterior Or Lead Page | 479,830 | 100.0% |
| Ask for a response | 476,891 | 99.4% |
| Address a concern | 472,273 | 98.4% |
| State the offer | 464,460 | 96.8% |
| Give proof or reassurance | 437,584 | 91.2% |
| State limits or disclosures | 408,997 | 85.2% |
| Explain Or Support | 340,265 | 70.9% |
| Component | Pieces | Share |
|---|---|---|
| Letter | 429,543 | 89.5% |
| Outer Envelope | 429,543 | 89.5% |
| Insert Or Terms Pages | 365,962 | 76.3% |
| Reply Device | 156,494 | 32.6% |
| Voucher Coupon Or Certificate | 88,037 | 18.3% |
| Self Mailer Body | 37,265 | 7.8% |
| Card Carrier Device | 7,420 | 1.5% |
| Undetermined Component | 3,992 | 0.8% |
| Booklet Or Catalog Body | 3,973 | 0.8% |
| Message sequence | Pieces | Share |
|---|---|---|
| Offer → Next Step → Proof → Qualification | 32,455 | 6.8% |
| Offer → Next Step → Qualification → Proof | 18,471 | 3.8% |
| Next Step → Offer → Proof → Qualification | 17,612 | 3.7% |
| Offer → Next Step → Qualification → Proof → Problem | 14,977 | 3.1% |
| Proof → Offer → Next Step → Qualification | 14,445 | 3.0% |
| Offer → Proof → Next Step → Qualification | 14,427 | 3.0% |
| Proof → Qualification → Offer → Next Step → Problem | 12,022 | 2.5% |
| Offer → Next Step → Proof → Qualification → Problem | 11,547 | 2.4% |
| Offer → Qualification → Next Step → Proof | 11,177 | 2.3% |
| Proof → Offer → Next Step → Qualification → Problem | 10,685 | 2.2% |
| Next Step → Offer → Qualification → Proof | 10,528 | 2.2% |
| Offer → Proof → Qualification → Next Step | 9,962 | 2.1% |
| Proof → Next Step → Qualification → Offer → Problem | 8,912 | 1.9% |
| Proof → Next Step → Offer → Qualification | 8,521 | 1.8% |
| Offer → Next Step → Proof | 7,939 | 1.7% |
| Next Step → Offer → Qualification | 7,216 | 1.5% |
| Next Step → Proof → Offer → Qualification | 7,084 | 1.5% |
| Offer → Next Step → Qualification | 6,931 | 1.4% |
| Next Step → Offer → Proof → Qualification → Problem | 6,690 | 1.4% |
| Next Step → Qualification → Offer → Proof → Problem | 6,594 | 1.4% |
| Offer → Proof → Next Step → Qualification → Problem | 6,563 | 1.4% |
| Proof → Qualification → Offer → Next Step | 5,966 | 1.2% |
| Proof → Offer → Qualification → Next Step → Problem | 5,923 | 1.2% |
| Proof → Next Step → Offer → Qualification → Problem | 5,855 | 1.2% |
| Offer → Next Step | 5,850 | 1.2% |
| Next Step → Offer → Proof | 5,806 | 1.2% |
| Next Step → Offer | 5,753 | 1.2% |
| Offer → Next Step → Proof → Problem → Qualification | 5,589 | 1.2% |
| Next Step → Offer → Qualification → Proof → Problem | 5,583 | 1.2% |
| Proof → Offer → Next Step | 5,566 | 1.2% |
| Proof → Offer → Qualification → Next Step | 5,548 | 1.2% |
| Next Step → Qualification → Offer → Proof | 5,546 | 1.2% |
| Qualification → Offer → Next Step → Proof | 5,502 | 1.1% |
| Offer → Proof → Qualification → Next Step → Problem | 5,384 | 1.1% |
| Offer → Qualification → Next Step → Proof → Problem | 5,339 | 1.1% |
| Qualification → Offer → Next Step → Proof → Problem | 5,136 | 1.1% |
| Proof → Qualification → Next Step → Offer | 4,896 | 1.0% |
| Offer → Proof → Next Step | 4,761 | 1.0% |
| Offer → Qualification → Proof → Next Step | 4,753 | 1.0% |
| Proof → Next Step → Offer | 4,735 | 1.0% |
| Next Step → Proof → Offer → Qualification → Problem | 4,573 | 1.0% |
| Qualification → Offer → Proof → Next Step | 4,343 | 0.9% |
| Next Step → Proof → Offer | 3,934 | 0.8% |
| Qualification → Next Step → Offer → Proof | 3,711 | 0.8% |
| Proof → Offer → Problem → Next Step → Qualification | 3,642 | 0.8% |
| Proof → Next Step → Qualification → Offer | 3,588 | 0.7% |
| Proof → Offer → Next Step → Problem → Qualification | 3,401 | 0.7% |
| Qualification → Next Step → Proof → Offer | 3,350 | 0.7% |
| Proof → Qualification → Next Step → Offer → Problem | 3,296 | 0.7% |
| Offer → Next Step → Problem → Proof → Qualification | 2,979 | 0.6% |
| Visual label | Pieces | Share |
|---|---|---|
| Image Led | 479,778 | 100.0% |
| People Or Lifestyle Text Adjacent | 342,971 | 71.5% |
| Product Or Service Text Adjacent | 278,453 | 58.0% |
| Diagram Or Comparison Text Adjacent | 203,114 | 42.3% |
| Copy Led | 40 | 0.0% |
| Balanced Image Copy | 12 | 0.0% |
Source: Expanded Insurance sector extract from 2,213,774 eligible records. 2,213,652 records were analyzed; 122 were explicitly unknown. Analysis received August 15, 2026. The expanded catalog has 2,213,774 eligible physical-mail records; 2,213,652 were analyzed and 122 remain unknown. Industry tables cover 1,873,585 records with an assigned industry. Computer-assigned labels can contain errors.
Compare nearby markets
Want this report as a PDF?
Everything above stays free to read here. If you want a copy to share with your team, we will email the insurance report as a PDF.